When a Global Capability Center grows faster than their sustainability plan can handle, issues emerge in the places you might not think to look. This includes rising energy demand, emissions, employee well being & governance standards.
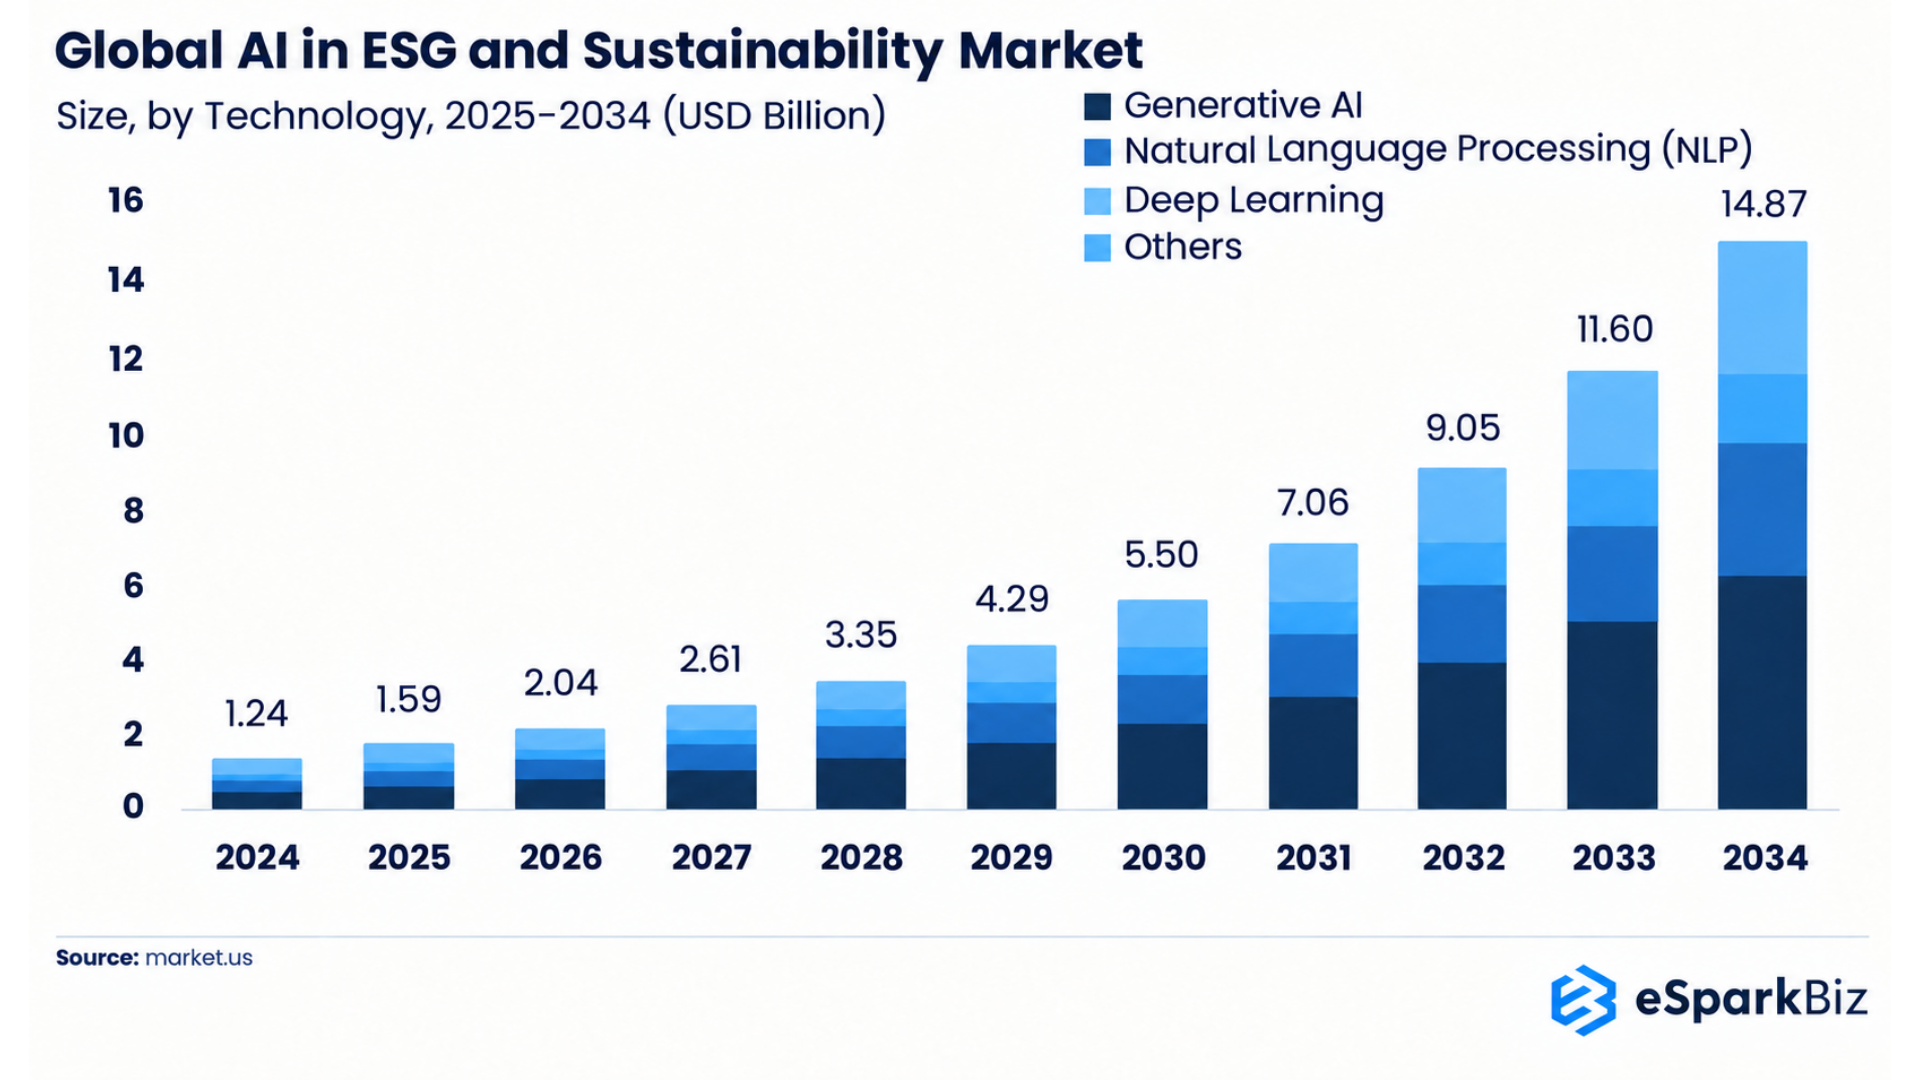
That is why ESG (Environmental, Social and Governance) is moving higher on a GCC agenda. The Global AI in ESG and Sustainability market is projected to reach $14.87B by 2034 at a 28.2% CAGR reflecting a broader shift toward technology led sustainability management.
The opportunity is bigger than meeting ESG expectations. For GCC leaders; it is about shaping operations that create business value while making sustainability part of the growth story.
Three Roles a Global Capability Center Plays in ESG: Where Strategy Meets Day to Day Execution
A Global Capability Center can shape ESG via three different ways; operational ownership, centralized delivery or a dedicated Center of Excellence.
| Role | What the GCC does | Example task | Parent owner | Data output |
| Own operation role | To manage its own ESG practices | Energy, and e-waste tracking | Facilities / HR | Site metrics |
| Delivery hub | Runs ESG processes for the parent | Data validation & reporting | CFO / Sustainability | Reporting data |
| ESG COE | Provides expertise & governance | ESG analytics & controls | Chief Sustainability Officer | Group insights |
Why Enterprises Are Expanding GCC Roles to Include ESG Work
The reason is not simply a headcount. GCCs can bring data, finance processes, technology teams and operational knowledge into one operating model structure.
Main drivers include,
- Centralized ESG data collection
- Dedicated reporting teams
- Access to finance, technology and analytics talent
- Consistent controls for recurring disclosures
- Faster response to parent company data requests
- Lower effort caused by fragmented spreadsheets & local processes
For a parent company the GCC can become the place where raw operational data becomes structured reporting input.
Navigating ESG Compliance: The Regulations That Matter to GCC Leaders
An India GCC doesn’t automatically have to follow every ESG reporting rule that may apply to the parent company. Whether it must report depends on the legal entity, listing status, jurisdiction and reporting structure.
- BRSR & BRSR Core: Indian ESG reporting frameworks that track sustainability metrics, emissions, energy use, workforce data and assurance requirements for qualifying listed companies
- CSRD: EU sustainability reporting framework. GCCs can support data collection, reporting preparation, data validation, and assurance readiness
- ISSB Standards (IFRS S1 and IFRS S2): Global standards covering sustainability, and climate disclosures. GCCs can manage ESG data, metrics and reporting inputs
| Framework | Who it applies to | What it requires | GCC data impact | Verification source |
| BRSR | Specified Indian listed entities | ESG disclosures | Indian entity data | SEBI |
| BRSR Core | Covered listed entities | Core metrics and assurance | KPI evidence | SEBI |
| CSRD | Covered EU companies | Sustainability disclosures | Subsidiary and value chain data | EU Official Journal |
| ISSB S1 | Companies applying ISSB | Sustainability related financial data | Risk & metric inputs | IFRS Foundation |
| ISSB S2 | Companies applying ISSB | Climate related disclosures | Scope 1, 2 and 3 inputs | IFRS Foundation |
Does an India Global Capability Center Need to Follow BRSR?
Not simply because it operates in India. The GCC needs to determine whether their own legal entity falls in the applicable SEBI requirements. A non listed GCC may instead supply information to a parent company that must meet BRSR, CSRD or another reporting requirement.
Turning ESG Goals Into Operations: How GCCs Can Lower Their Environmental Impact
A GCC’s environmental work starts with the assets it controls; office space, electricity, water, commuting, waste and technology use.
| Lever | What changes | Metric | Data owner |
| Green building | Efficient office design | Energy / water use | Facilities |
| Renewable power | Clean electricity sourcing | Renewable share | Facilities / Finance |
| Commute | Lower emission transport | Commute emissions | Admin |
| e-waste | Responsible disposal | e-waste volume | IT |
| Cloud | Better resource use | Cloud energy / emissions data | IT |
| Water | Metering and reuse | Water per seat | Facilities |
LEED provides building certification criteria covering areas such as energy, water, materials and indoor environmental quality. IGBC’s Green New Buildings, and Green Campus systems also address energy, water, waste, transportation and occupant wellbeing.
The Social and Governance Responsibilities Global Capability Centers Cannot Overlook
ESG goes beyond just tracking meters of electricity. A GCC must also take care of the responsibility for how it hires, supports employees, manages suppliers and protects to information.
Core areas include,
- Workforce diversity & pay equity
- Employee health & well being
- Tier 2 city hiring where appropriate
- ESG training and policy awareness
- Supplier codes of conduct
- Data privacy and access controls
- ESG governance councils
- Internal review & escalation procedures
The governance layer is very important when the GCC works with sensitive information like employee, supplier or emissions data for their parent company.
🌐 Global Momentum
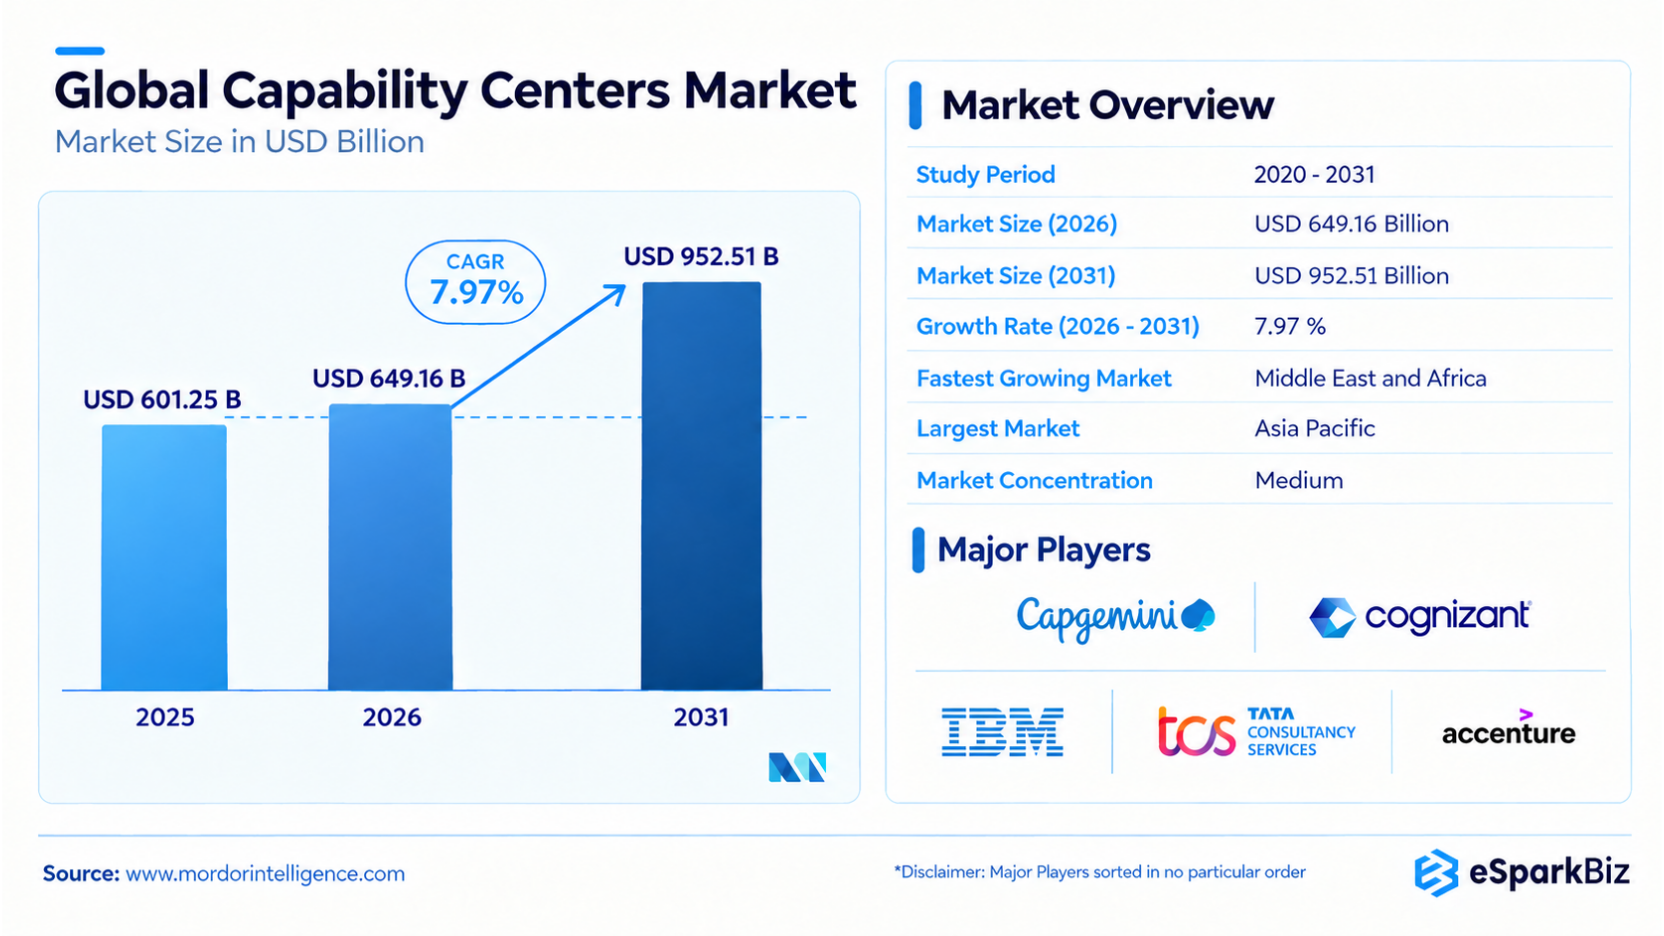
The global GCC market valued at USD 649.16B is projected to reach USD 952.51B by 2031 growing at a 7.97% CAGR. This reflects their expansion in the global GCC operations.
The Metrics That Matter for ESG Performance: Which KPIs Should a GCC Track
Choose KPIs (Key Performance Indicators) that link GCC operations with ESG goals, reporting requirements and measurable results of business.
| Pillar | KPI | Unit | Data source | Framework link |
| For environment | Energy per seat | kWh | Utility data | BRSR / ISSB |
| For environment | Renewable share | % | Energy records | BRSR / ISSB |
| For environment | Scope 1 & 2 | tCO₂e | Emissions calculation | ISSB |
| For environment | e-waste | kg | IT records | ESG reporting |
| To social | Women in workforce | % | HRIS | BRSR |
| To social | Attrition | % | HRIS | Parent KPI |
| To social | Training completion | % | LMS | Governance |
| For governance | Policy completion | % | Compliance system | Governance |
| For governance | Data exceptions | Count | ESG platform | Controls |
Who Owns ESG Data Between a US Parent Company and a GCC in India
The best way to organize this is to keep data ownership separate from the disclosure ownership. The GCC handles collecting, validating, calculating and preparing data. The parent company usually sets group methodology, decides what matters most and signs the final disclosure.
| Task | Parent company | GCC | Sign off authority |
| ESG policy | A | C | Parent |
| Data collection | C | R | GCC |
| Validation | A | R | Parent / GCC |
| Calculations | A | R | Parent |
| Disclosure pack | A | R | Parent |
| Assurance support | A | R | Parent |
| Final report | R | C | Parent |
R = Responsible, A = Accountable, C = Consulted
What Technology Does GCC ESG Work Need: Building a Digital Backbone for Data and Reporting
A practical ESG tech setup brings together five main parts; a data platform for ESG information, tools to calculate emissions, a way to share supplier details, visual reports as dashboards and an audit trail of all changes made.
No single software package will automatically solve every of the ESG requirements. EY notes the need for technology, and process support as GCCs take on ESG work.
The technology should answer five questions; Where did the data come from? Who changed it? Which of the calculations produced the result? Who reviewed it? and Which report uses it?
What Are the Biggest ESG Challenges GCCs Face in Practice
Missing data can weaken ESG reporting before a dashboard becomes the problem. GCCs must address ownership, quality, controls and assurance readiness.
| Risk | Cause | Control | Owner |
| Data fragmentation | Multiple systems | Standard data model | ESG lead |
| Skills gap | Limited ESG expertise | Training and hiring | HR / ESG |
| Scope 3 gaps | Supplier data limits | Supplier data rules | Procurement |
| Boundary confusion | Unclear ownership | Defined reporting boundary | Parent |
| Assurance gaps | Weak evidence | Audit trail and controls | Finance |
| Greenwashing exposure | Unsupported claims | Evidence review | Sustainability |
EY identifies the evolving nature of ESG functions, and skills gaps as challenges for GCCs seeking a larger ESG role.
Is Your GCC Ready for the Next Wave of ESG Expectations
See where your GCC stands on ESG maturity right now. Learn what steps you need to take to improve your reporting, controls, and governance.
| Stage | Typical activities | Data practice | Next step |
| 1. Basic tracking | Local ESG activities | Spreadsheets | Define ownership |
| 2. Structured reporting | Recurring collection | Central repository | Add controls |
| 3. Managed reporting | Clearly defined processes | A validated dataset | Prepare assurance |
| 4. ESG COE | Group ESG services | Governed data platform | Expand analytics |
A GCC at Stage 1 should avoid starting with costly technology programs. Instead first set up clear ownership, define boundaries & gather baseline data.
Also Read: Top GCC Talent Trends : Key Workforce Shifts in India
How Should an Enterprise Build ESG Capability in a GCC: Putting the Right People, Processes and Technology in Place
To build a strong ESG foundation in your GCC by following a clear 12 month roadmap plan. Start with a baseline assessment then move to setting up controls, preparing reports and getting ready for assurance readiness.
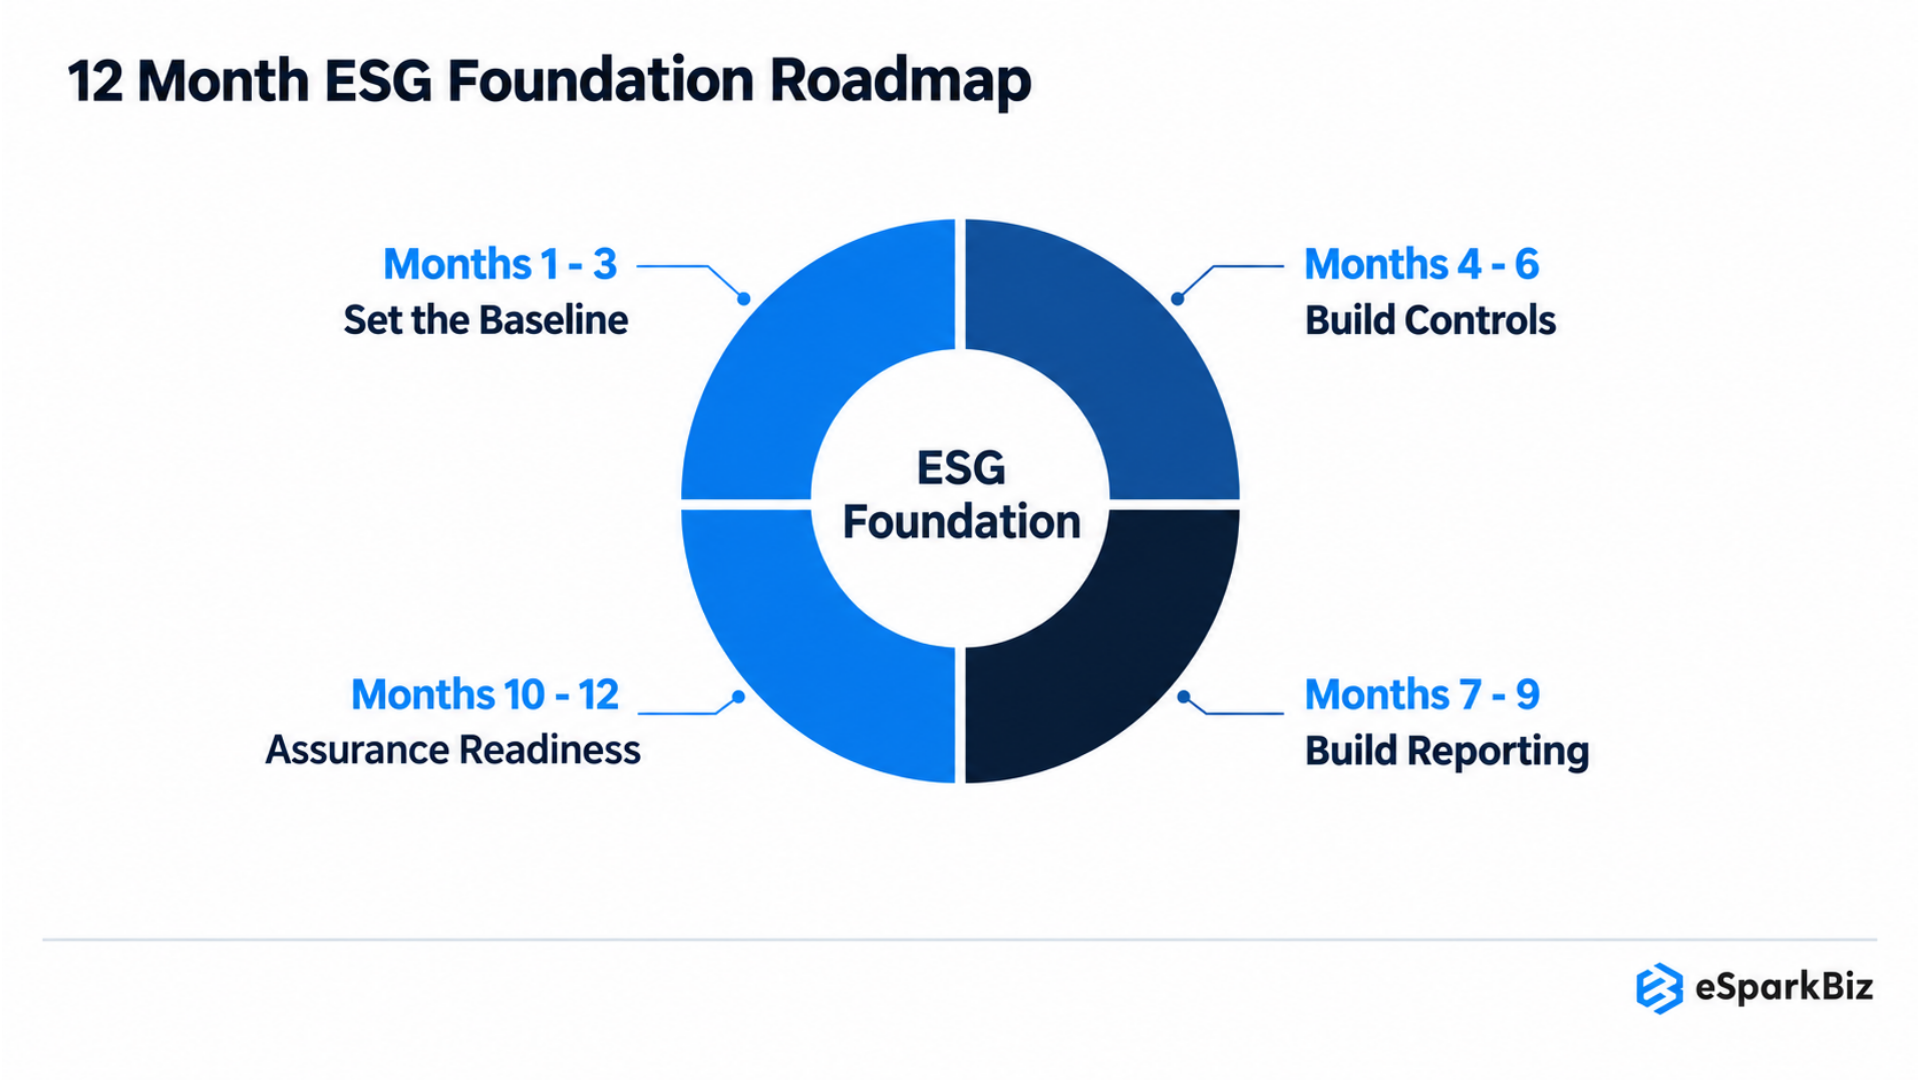
- Months 1 to 3: To define scope, ownership, reporting boundaries and baseline metrics
- Months 4 to 6: Creating a data source, controls, calculation methods and reporting calendars
- Months 7 to 9: To build dashboards, supplier data processes & evidence repositories
- Months 10 to 12: Run a mock reporting cycle, and prepare for an assurance
What Should a First Year ESG Budget Include?
Start with real costs not a guess. Build your budget based on what actually drives expenses;
- ESG reporting tools, data controls and assurance fees
- Green building or facilities changes
- Renewable energy procurement
- ESG specialists & training
- Supplier data collection
- GCC setup, legal registration and compliance costs
First year costs depend on team size, reporting scope, technology requirements and assurance needs. Confirm vendor quotes before assigning budget ranges.
For ESG heavy GCCs, a BOT model can help establish reporting processes and transfer ownership later, while an in house model gives the parent company direct control from launch.
When Should You Bring in a Partner to Set Up ESG Capability in Your GCC?
A GCC setup partner can help US companies establish ESG data governance, reporting workflows and ownership structures in India. eSparkBiz structures the GCC launch around agreed responsibilities, operating processes and milestones for a GCC.
For US teams, confirm the contracting entity, agreement terms and working-hour overlap directly with the provider. A partner is worth considering when your GCC lacks the internal expertise or systems to manage ESG reporting.
Before selecting the best partner for your needs, assess;
- ESG data ownership and reporting requirements
- Governance, compliance and data access controls
- US & India working-hour coordination
- Team onboarding, knowledge transfer and handover
A US company building an ESG team can use partner support to establish reporting workflows before transferring day to day ownership to their internal team. eSparkBiz has 400+ professionals and holds ISO 27001:2022 certification.
Should You Build, Partner or Take a Hybrid Approach?
Choose the right ESG delivery model based on control, expertise and GCC maturity. Look at three main options; building it yourself, working with a partner or using a mix of both called hybrid approaches. Each choice has different benefits you can count on.
| Decision factor | In house build | Build operate transfer | Hybrid |
| Control | High | High after transfer | High |
| Initial speed | Lower | Higher | Medium |
| Internal expertise | Required | Built during engagement | Shared |
| Cost drivers | Hiring, systems | Team, transition, systems | Internal + partner |
| Best fit | Mature ESG function | New GCC capability | Mixed maturity |
| Partner value | Limited when the skills already exist | High during build phase | High for a targeted gap |
A partner brings limited value when a parent company already has well developed ESG practices, skilled staff and working reporting technology in place. A partner becomes more useful to a GCC when governance structures, data management systems and reporting procedures need to be built from scratch.
Frequently Asked Questions
Who owns ESG data between a Global Capability Center and parent company?
A Global Capability Center can own ESG data collection, validation and operational records within its scope. The parent company defines reporting rules & materiality. The parent normally remains accountable for the consolidated disclosures.
Why do BRSR and CSRD create different ESG data needs for GCCs?
BRSR is an Indian reporting framework administered by SEBI for the specified listed entities. CSRD is an EU sustainability reporting framework that applies based on well defined group conditions. A GCC may provide data without being directly subject to obligations of the parent’s reporting.
Which ESG certifications should a new Global Capability Center consider for its office?
LEED, and IGBC are useful starting points for green office certification especially when energy, water, waste and occupant wellbeing matter.
Where does a GCC fit into Scope 3 emissions reporting?
A GCC can provide Scope 3 data for operations, suppliers, commuting & travel. The parent defines the reporting boundaries and methodology. IFRS S2 references the GHG Protocol for Scope 1, 2 and 3 measurement.
Are ESG audits mandatory for every India GCC?
No. ESG audit, or assurance duties depend on the legal entity, applicable reporting framework, parent requirements and specific disclosure obligations.
Do GCCs need to report Scope 3 emissions?
Not every GCC has the same reporting duty. Scope 3 becomes related when the parent framework requires for value chain emissions, or the GCC contributes material emissions data.
Why should the ESG be included in a Global Capability Center location and office planning?
ESG decisions made during selection of sites that may influence energy use, renewable power access, water consumption, commuting emissions and green building opportunities from the start.
Can a GCC reduce its carbon footprint without changing its core operations?
Yes. GCCs can reduce their carbon footprint using renewable electricity, efficient buildings, lower emission commuting, cloud efficiency and responsible e-waste management. eSparkBiz can support the execution layer by using methods likely;
- Measure office and cloud emissions
- To set reduction targets by source
- Track renewable energy consumption
- To strengthen ESG reporting processes
 August 17, 2026